Thursday, October 12, 2023

FIRST HOME SELLS FOR OVER $1,000,000 IN SCCL

The first home to be listed for over $1M in SCCL has become the first home to sell for over $1M.  The home, a Cumberland Hall with a beautifully finished basement, sunroom, patio, large screened porch, and a lovely golf course view, listed for $1,296,000 on August 3rd and went under contract two days later.  It closed on October 12th for $1,175,000.  


As I noted in my posting on August 26, prices have been rising here in Sun City Carolina LakesHomes that are in excellent condition and are priced right generally sell faster and often at a higher price than those that need work.  Since that posting, it seems that many folks have decided this is a great time to sell. That being said, some are now listing higher than current comps would suggest is appropriate, and are having to reduce their asking price.  Yes, prices are going up, but shooting for the stars isn't always a great plan.  
 
Currently, one Manor home is listed at $1.1M and another Manor is listed at $850K.  There are three homes (1 Manor and 2 Summits) listed between $749,900 and $789,000, and one Summit went under contract at a list price of $774,900 this month.  
 
If you'd like to get daily updates on current listings in SCCL, TreeTops, or other nearby communities, please contact me.  
 
Remember that I'm always available to  answer your real estate questions and help you in whatever way I can.


Growing Your Net Worth with Homeownership

Article Courtesy of Keeping Current Matters/The KCM Blog

Take a moment to imagine where you want to be in a few years. You might be thinking about your job, money, wanting more stability, or goals you want to reach soon. Is homeownership a part of that vision? If it is, you should know owning a home has a whole lot of financial benefits.

One of the many reasons to buy a home is that it’s a great way to build wealth and gain financial stability. That’s because the value of most homes increases over time, which in turn grows your net worth. Here’s how home values are rising right now. According to Zillow:

“The total value of the U.S. housing market – the sum of Zillow’s estimated value for every U.S. home – is now slightly less than $52 trillion, which is $1.1 trillion higher than the previous peak reached last June.”

Basically, homeownership is a tremendous wealth-building tool. And with home values back on the rise across the nation, now might be a good time to consider if owning a home is something you want to reach for.

Here’s a look at some data to see how much owning a home can really make a difference in your life.

Household Net Worth Is Rising

Data shows that while those in the top 1% saw the most dramatic net worth increase, people from every single tax bracket have seen their wealth grow over the past few years (see graph below):

For many of those people, the rising value of their home plays a big part in that.

Owning a Home Helps You Achieve Financial Success

You can tell homeownership had a lot to do with that growth because there’s a significant net worth gap between homeowners and renters. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:

 “. . . homeownership is a catalyst for building wealth for people from all walks of life. A monthly mortgage payment is often considered a forced savings account that helps homeowners build a net worth about 40 times higher than that of a renter.”

The big reason why? Homeowner’s build equity. Home equity is the value of your home minus the amount you owe on your mortgage. And for most homeowners, that’s the largest contributor to their net worth. Here’s the data from First American to prove it (see graph below):


The blue portion of each bar represents housing as a portion of net worth – and it’s clearly a bigger contributor than other investments like stocks, gold, and cryptocurrencies. As you can see, across different income levels, homeownership does more to build the average household’s wealth than anything else.

Bottom Line

One of the biggest benefits of owning a home is that it can provide an avenue to grow your net worth.

Monday, October 9, 2023

Key Skills You Need Your Listing Agent To Have

Article Courtesy of Keeping Current Matters / The KCM Blog

Key Skills You Need Your Listing Agent To HaveSelling your house is a big decision. And that can make it feel both exciting and a little bit nerve-wracking. But the key to a successful sale is finding the perfect listing agent to work with you throughout the process. A listing agent, also known as a seller’s agent, helps market and sell your house while advocating for you every step of the way.

But, how do you know you’ve found the perfect match in an agent? Here are three key skills you’ll want your listing agent to have.

They Price Your House Based on the Latest Data

While it may be tempting to pick the agent who suggests the highest asking price for your house, that strategy may cost you. It’s easy to get caught up in the excitement when you see a bigger number, but overpricing your house can have consequences. It could mean it’ll sit on the market longer because the higher price is actually deterring buyers.

Instead, you want to pick an agent who’s going to have an open conversation about how they think you should price your house and why. A great agent will base their pricing strategy on solid data. They won’t throw out a number just to win your listing. Instead, they’ll show you the facts, explain their pricing strategy, and make sure you’re on the same page. As NerdWallet explains:

“An agent who recommends the highest price isn’t always the best choice. Choose an agent who backs up the recommendation with market knowledge.”

They’re a Great Negotiator

The home-selling process can be emotional, especially if you’ve been in your house for a long time. You’re connected to it and have a lot of memories there. This can make the negotiation process harder. That’s where a trusted professional comes in.

A skilled listing agent will be calm under pressure and will be your point-person in all of those conversations. Their experience in handling the back-and-forth gives you with the peace of mind that you’ve got someone on your side who’s got your best interests in mind throughout this journey.

They’re a Skilled Problem Solver

At the heart of it all, a listing agent’s main priority is to get your house sold. A great agent never loses sight of that goal and will help you prioritize your needs above all else. If they identify any necessary steps you need to take, they’ll be open with you about it. Their commitment to your success means they’ll work with you to address any potential roadblocks and find creative solutions to anything that pops up along the way.

BankRate explains it like this:

“Just as important as the knowledge and experience agents bring is their ability to guide you smoothly through the process. Above all, go with an agent you trust and will feel comfortable with. . .”

Bottom Line

Whether you're a first-time seller or you’ve been through selling a house before, a great listing agent is the key to success. Connect with a real estate professional so you have a skilled local expert by your side to guide you through every step of the process.

Monday, September 25, 2023

Beginning with Pre-Approval

 Article Courtesy of Keeping Current Matters/The KCM Blog

If you’re looking to buy a home this fall, there are a few things you need to know. Affordability is tight with today’s mortgage rates and rising home prices. At the same time, there’s a limited number of homes on the market right now and that’s creating some competition among buyers. But, if you’re strategic, there are ways to navigate these waters. The first thing you’ll want to do is get pre-approved for a mortgage. That way you’ll know your numbers and can set yourself up for success from the start of your home search.

What Pre-Approval Does for You

To understand why it’s such an important step, you need to know what pre-approval is. As part of the homebuying process, a lender looks at your finances to determine what they’d be willing to loan you. From there, your lender will give you a pre-approval letter to help you know how much money you can borrow. Freddie Mac explains it like this:

A pre-approval is an indication from your lender that they are willing to lend you a certain amount of money to buy your future home. . . . Keep in mind that the loan amount in the pre-approval letter is the lender’s maximum offer. Ultimately, you should only borrow an amount you are comfortable repaying.”

Basically, pre-approval gives you critical information about the homebuying process that’ll help you understand how much you may be able to borrow. Why does this help you, especially today? With higher mortgage rates and home prices impacting affordability for many buyers right now, a solid understanding of your numbers is even more important so you can truly wrap your head around your options.

Pre-Approval Helps Show Sellers You’re a Serious Buyer

Let’s face it, there are more buyers looking to buy than there are homes available for sale and that imbalance is creating some competition among homebuyers. That means you could see yourself in a multiple-offer scenario when you make an offer on a home. But getting pre-approved for a mortgage can help you stand out from other hopeful buyers.

As an article from Wall Street Journal (WSJ) says:

If you plan to use a mortgage for your home purchase, preapproval should be among the first steps in your search process. Not only can getting preapproved help you zero in on the right price range, but it can give you a leg up on other buyers, too.”

Pre-approval shows the seller you’re a serious buyer that’s already undergone a credit and financial check, making it more likely that the sale will move forward without unexpected delays or financial issues.

Bottom Line

Getting pre-approved is an important first step when you’re buying a home. The more prepared you are, the better chance you have of getting the home you want. Connect with a trusted lender so you have the tools you need to purchase a home in today’s market.

Monday, September 11, 2023

Planning to Retire? Your Equity Can Help You Make a Move

 Article Courtesy of Keeping Current Matters/The KCM Blog

Reaching retirement is a significant milestone in life, bringing with it a lot of change and new opportunities. As the door to this exciting chapter opens, one thing you may be considering is selling your house and finding a home better suited for your evolving needs.

Fortunately, you may be in a better position to make a move than you realize. Here are a few reasons why.

Consider How Long You’ve Been in Your Home

From 1985 to 2009, the average length of time homeowners stayed in their homes was roughly six years. But according to the National Association of Realtors (NAR), that number is higher today. Since 2010, the average home tenure is just over nine years (see graph below):

This means many homeowners have been living in their houses even longer in recent years. When you live in a home for such a significant amount of time, it’s natural for you to experience changes in your life while you’re in that house. As those life changes and milestones happen, your needs may change. And if your current home no longer meets them, you may have better options waiting for you.

Consider the Equity You’ve Gained

And, if you’ve been in your home for more than a few years, you’ve likely built-up substantial equity that can fuel your next move. That’s because you gain equity as you pay down your loan and as home prices appreciate. And, the longer you’ve been in your home, the more you may have gained. Data from the Federal Housing Finance Agency (FHFA) illustrates that point (see graph below): 


 While home prices vary by area, the national average shows the typical homeowner who’s been in their house for five years saw it increase in value by nearly 60%. And the average homeowner who’s owned their home for 30 years saw it almost triple in value over that time.

Whether you’re looking to downsize, relocate to a dream destination, or move so you live closer to friends or loved ones, that equity can help. Whatever your home goals are, a trusted real estate agent can work with you to find the best option. They’ll help you sell your current house and guide you as you buy the home that’s right for you and your lifestyle today.

Bottom Line

As you plan for your retirement, connect with a local real estate agent to find out how much equity you’ve built up over the years and plan how you can use it toward the purchase of a home that fits your changing needs.


Tuesday, August 29, 2023

Why You May Still Want To Sell Your House After All

 Article Courtesy of Keeping Current Matters / The KCM Blog

Even though you may feel reluctant to sell your house because you don’t want to take on a mortgage rate that’s higher than the one you have now, there’s more to consider. While the financial side of things does matter, your personal needs may actually matter just as much. As an article from Bankrate says:

Deciding whether it’s the right time to sell your home is a very personal decision. There are numerous important questions to consider, both financial and lifestyle-based, before putting your home on the market.”

So, ask yourself this: why did I want to move in the first place?

Chances are your primary motivation wasn’t just financial in nature. Why you’re really thinking about selling likely has more to do with something changing in your life or a shift in what you need out of your house.

Reasons Homeowners Still Need To Sell Today

Let’s explore some of the most common reasons sellers are moving today. A recent article from Builder Online helps shed light on this. In this research, they identified the following categories:

  • Marriage – If you just got married, you may find you either need more space than you currently have, or the two of you want to find a new place you picked out together.
  • Divorce – If you’re getting separated or are divorcing your partner, chances are it’ll be difficult to live under the same roof. Selling the place you have, so you can own get your own spot, may be necessary.
  • Births – If your household is growing, you may need more square footage, including more bedrooms. If you’re running out of room for everyone, you may not be able to wait to move.
  • Deaths – If you’ve recently lost a loved one, it can be hard to spend time in that home. You may need to move for financial reasons or because you no longer need all the space.
  • Retirement – If you’re in the process of retiring, or you just did, you may be looking to downsize to cut costs, relocate to be closer to loved ones, or move to a dream location. In this new phase of life, your current home may not be able to deliver what you need. 

You may find you share one of these top motivators. If any of these resonate with you, it may be time to move so you can find a house better suited to your changing needs. A survey from Realtor.com finds other sellers are in the same boat. It says, 1 in 4 sellers are choosing to move for personal reasons, even with current mortgage rates:

“. . . more than half of seller-buyers (56%) who are planning to sell in the next 12 months said they are waiting for rates to come down, while 25% need to sell soon for personal reasons.”

If you need to sell now because something in your own life has changed, don’t let rates hold you back from what you want. You have options to help make that move possible. You can use the equity you already have in your current home toward your next purchase. And with how much equity homeowners have right now, you may be able to finance less than you’d expect, or pay all cash to avoid borrowing at all.

Bottom Line

When you're ready to prioritize your changing needs, reach out to a trusted real estate professional. They can help you list your house and find a home that delivers on everything you're looking for.

Saturday, August 26, 2023

SCCL Prices are Rising

8/26/23

In spite of rising interest rates, which are making it especially difficult for first time buyers, the market remains strong here in Sun City Carolina Lakes, as many buyers are moving from homes where they have lived for a long time and have a good amount of equity to put into a new home. 

Pricing in SCCL has changed considerably, with some homes being listed at new highs for the community.  Below is a summary of all homes in SCCL that have been listed at $650,000 or higher.  Until June of 2022, no Summit home (mid-size collection) ever listed above $597,900.  Since that time, five Summits (actually one that sold last year and is currently for sale again) have listed or sold for over $670,000, with two basement homes selling for just under $700,000 and one home currently listed at $824,900.

The other homes listed below are all Manor homes and, until July 2023, when a Chestnut Garden with a basement listed and sold for $800,000, no Manor Home had listed or sold for more than $759,000.  This month, a Cumberland Hall with a basement listed at $1,296,000, setting a new record for a listing price in SCCL.  The actual sale price will not be made public until the property closes.

Homes that are in excellent condition and are priced right generally sell faster and often at a higher price than those that need work and linger on the market.  The number of  Days on Market (DOM) column below shows that of the 28 UC or CLOSED homes listed, 20 went under contract in 7 days or less, with 16 going under contract in 3 days or less.  Fourteen of the homes below sold at or above list price.

Click on chart to enlarge.


Tuesday, August 22, 2023

Why You Don’t Need To Fear the Return of Adjustable-Rate Mortgages

Article Courtesy of Keeping Current Matters/The KCM Blog

 Why You Don’t Need To Fear the Return of Adjustable-Rate Mortgages

If you remember the housing crash back in 2008, you may recall just how popular adjustable-rate mortgages (ARMs) were back then. And after years of being virtually nonexistent, more people are once again using ARMs when buying a home. Let’s break down why that’s happening and why this isn’t cause for concern.


Why ARMs Have Gained Popularity More Recently

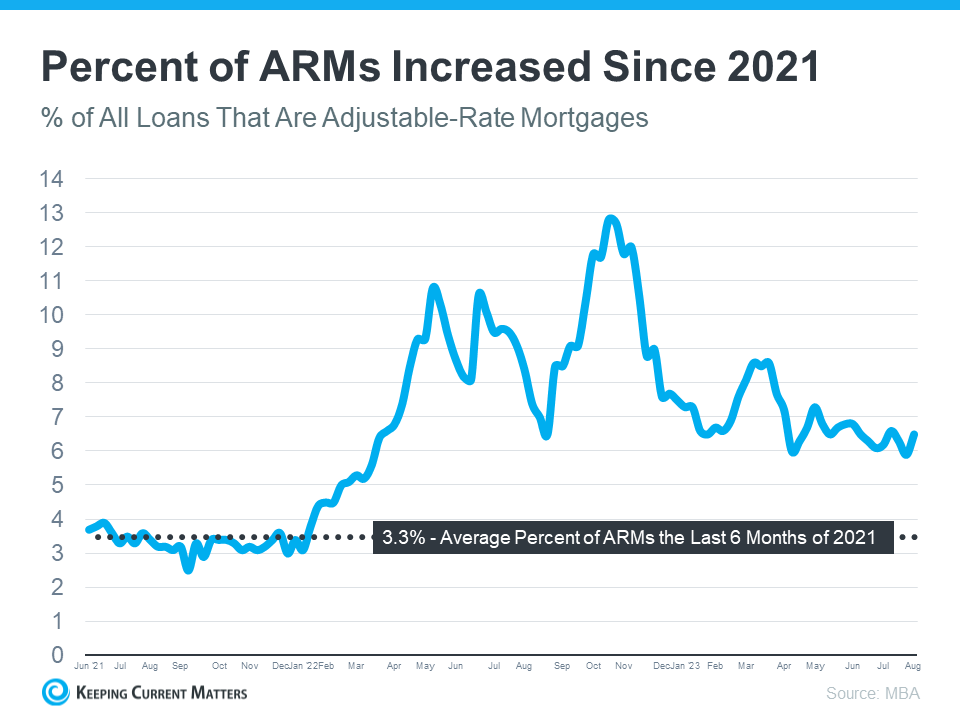
This graph uses data from the Mortgage Bankers Association (MBA) to show how the percentage of adjustable-rate mortgages has increased over the past few years: 

undefined

As the graph conveys, after hovering around 3% of all mortgages in 2021, many more homeowners turned to adjustable-rate mortgages again last year. There’s a simple explanation for that increase. Last year is when mortgage rates climbed dramatically. With higher borrowing costs, some homeowners decided to take out this type of loan because traditional borrowing costs were high, and an ARM gave them a lower rate. 

Why Today’s ARMs Aren’t Like the Ones in 2008

To put things into perspective, let’s remember these aren’t like the ARMs that became popular leading up to 2008. Part of what caused the housing crash was loose lending standards. Back then, when a buyer got an ARM, banks and lenders didn’t require proof of their employment, assets, income, etc. Basically, people were getting loans that they shouldn’t have been awarded. This set many homeowners up for trouble because they couldn’t pay back the loans that they never had to qualify for in the first place.

This time around, lending standards are different. Banks and lenders learned from the crash, and now they verify income, assets, employment, and more. This means today’s buyers actually have to qualify for their loans and show they’ll be able to repay them.

Archana Pradhan, Economist at CoreLogic, explains the difference between then and now:

“Around 60% of Adjustable-Rate Mortgages (ARM) that were originated in 2007 were low- or no-documentation loans . . . Similarly, in 2005, 29% of ARM borrowers had credit scores below 640 . . . Currently, almost all conventional loans, including both ARMs and Fixed-Rate Mortgages, require full documentation, are amortized, and are made to borrowers with credit scores above 640.”

In simple terms, Laurie Goodman at Urban Institute helps drive this point home by saying:

“Today’s Adjustable-Rate Mortgages are no riskier than other mortgage products and their lower monthly payments could increase access to homeownership for more potential buyers.”

Bottom Line

If you’re worried today’s adjustable-rate mortgages are like the ones from the housing crash, rest assured, things are different this time.

Tuesday, August 15, 2023

Equity Is a Game Changer for Homeowners Looking To Sell

Article Courtesy of Keeping Current Matters/The KCM Blog

If you’re a homeowner, you might be torn on whether or not to sell your house right now. Maybe that’s because you don’t want to take on a higher mortgage rate on your next home. If that’s your biggest hurdle, understanding your equity may be exactly what you need to help you feel more comfortable making your move.


What Equity Is and How It Works

Equity is the current value of your home minus what you owe on the loan. And recently, that equity has been growing far faster than you may expect.

Over the last few years, home prices rose dramatically, and that gave your equity a big boost very quickly. While the market has started to normalize, there’s still an imbalance between the number of homes available for sale and the number of buyers looking to make a purchase. And it’s because homes are in such high demand that prices are back on the rise today. Rob Barber, CEO of ATTOM, a property data provider, explains:

“Equity levels were high even during the recent downturn, and now they are going back up and better than ever.”

How Equity Benefits You in Today’s Market

With today’s affordability challenges, that equity can be a game changer when you move. Here’s why. Based on data from ATTOM and the Census, nearly two-thirds (68.7%) of homeowners have either paid off their mortgages or have at least 50% equity (see chart below):

That means roughly 70% have a tremendous amount of equity right now.

Once you sell your house, you can use your equity to help with your next purchase. It could be some (if not all) of what you’ll need for your next down payment. It may even be enough to allow you to put a considerably larger down payment on your next home, so you don’t have to finance quite as much. And, if you’ve been in your current house for years, you may have even built up enough equity to pay in all cash. If that’s true for you, you’d be able to avoid borrowing altogether, so you wouldn’t have to worry about today’s mortgage rates.

How To Find Out How Much Equity You Have

The best way to learn how much you have is to reach out to a trusted real estate agent for a Professional Equity Assessment Report (PEAR).

Bottom Line

If you’re planning to make a move, the equity you’ve gained can make a big impact. To find out just how much equity you have in your current home and how you can use it to fuel your next purchase, connect with a trusted real estate advisor.


Tuesday, August 1, 2023

Sellers: Don’t Let These Two Things Hold You Back

Article Courtesy of Keeping Current Matter / The KCM Blog

Many homeowners thinking about selling have two key things holding them back. That’s feeling locked in by today’s higher mortgage rates and worrying they won’t be able to find something to buy while supply is so low. Let’s dive into each challenge and give you some helpful advice on how to overcome these obstacles.

Challenge #1: The Reluctance to Take on a Higher Mortgage Rate

According to the Federal Housing Finance Agency (FHFA), the average interest rate for current homeowners with mortgages is less than 4% (see graph below):


 But today, the typical 30-year fixed mortgage rate offered to buyers is closer to 7%. As a result, many homeowners are opting to stay put instead of moving to another home with a higher borrowing cost. This is a situation known as the mortgage rate lock-in effect.

The Advice: Waiting May Not Pay Off

While experts project mortgage rates will gradually fall this year as inflation cools, that doesn’t necessarily mean you should wait to sell. Mortgage rates are notoriously hard to predict. And, right now home prices are back on the rise. If you move now, you’ll at least beat rising home prices when you buy your next home. And, if experts are right and rates fall, you can always refinance later if that happens.

Challenge #2: The Fear of Not Finding Something to Buy

When so many homeowners are reluctant to take on a higher rate, fewer homes are going to come onto the market. That’s going to keep inventory low. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:

Inventory will remain tight in the coming months and even for the next couple of years. Some homeowners are unwilling to trade up or trade down after locking in historically-low mortgage rates in recent years.”

Even though you know this limited housing supply helps your house stand out to eager buyers, it may also make you feel hesitant to sell because you don’t want to struggle to find something to purchase.

The Advice: Broaden Your Search

If fear you won’t be able to find your next home is the primary thing holding you back, remember to consider all your options. Looking at all housing types including condos, townhouses, and even newly built homes can help give you more to choose from. Plus, if you’re able to work fully remote or hybrid, you may be able to consider areas you hadn’t previously searched. If you can look further from your place of work, you may have more affordable options.

Bottom Line

Instead of focusing on the challenges, focus on what you can control. Reach out to a local agent so you’re working with a professional who has the experience to navigate these waters and find the perfect home for you.