Friday, June 30, 2023

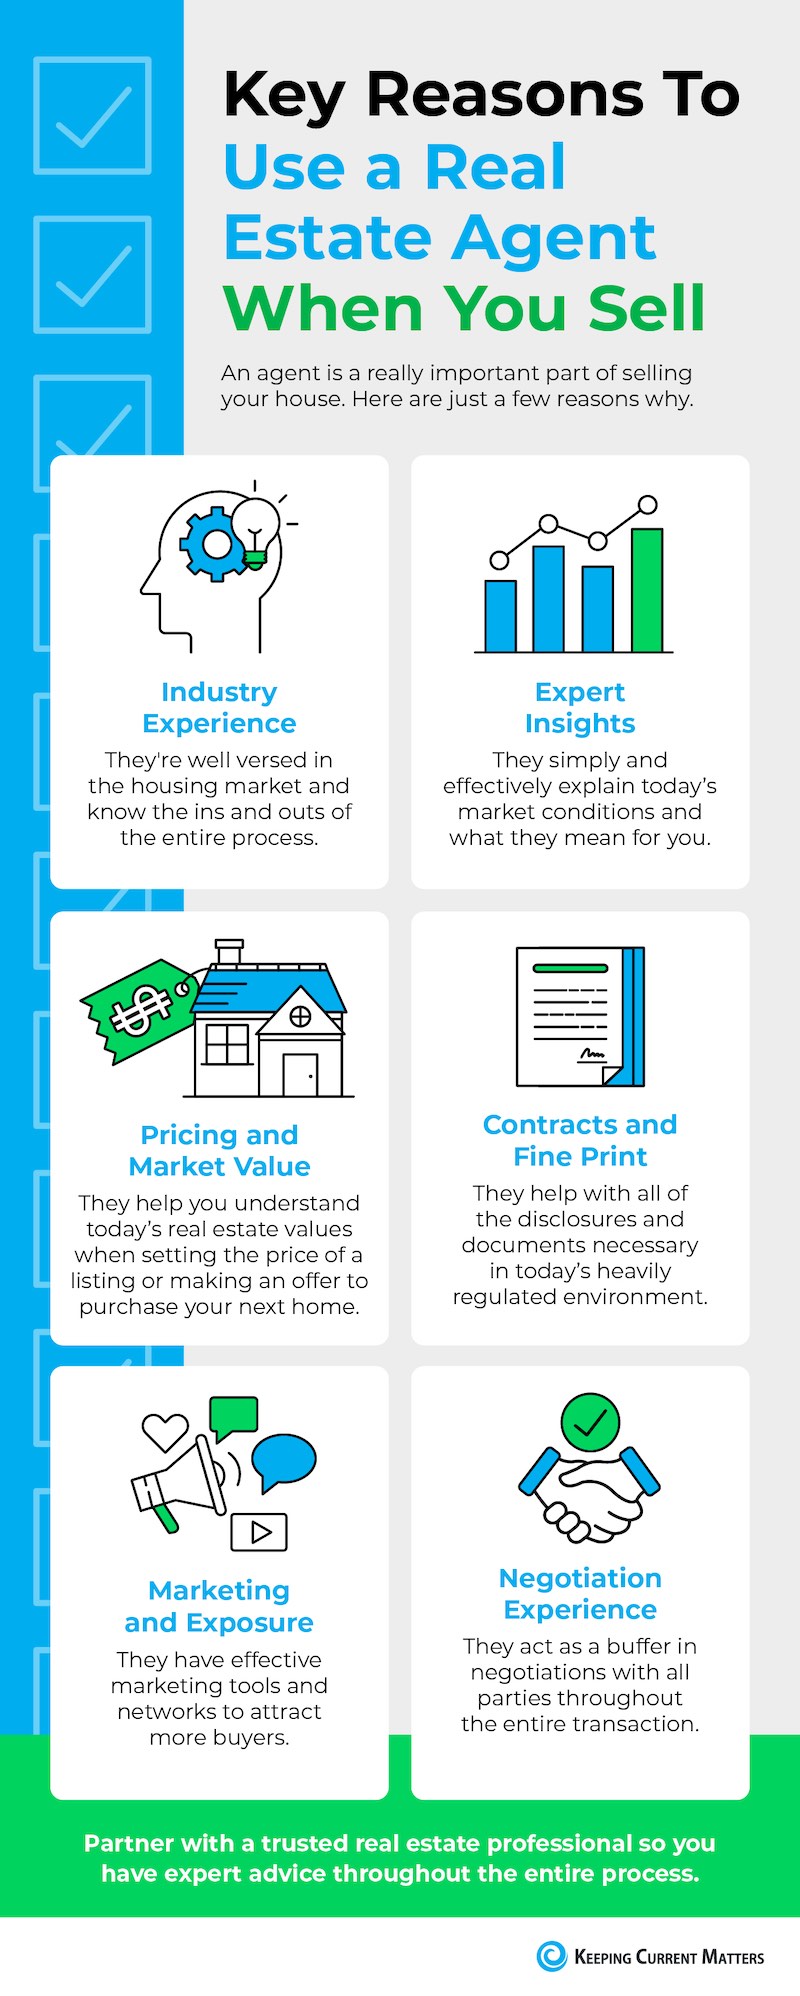
Key Reasons To Use a Real Estate Agent When You Sell [INFOGRAPHIC]

Infographic Courtesy of Keeping Current Matters / The KCM Blog

Some Highlights

  • An agent is a really important part of selling your home because they bring a lot of skill and expertise to the sales process.
  • They’ll explain what’s happening today, what that means for you, and how to price and market your house. They’re also skilled negotiators and well versed in the contracts and disclosures involved.
  • Connect with a local real estate agent to ensure you have an expert helping you sell your house successfully.

Wednesday, June 21, 2023

Why the Median Home Price Is Meaningless in Today’s Market

 Article Courtesy of Keeping Current Matters/The KCM Blog

The National Association of Realtors (NAR) will release its latest Existing Home Sales (EHS) report later this week. This monthly report provides information on the sales volume and price trend for previously owned homes. In the upcoming release, it’ll likely say home prices are down. This may feel a bit confusing, especially if you’ve been following along and seeing the blogs saying that home prices have bottomed out and turned a corner.

So, why will this likely say home prices are falling when so many other price reports say they’re going back up? It all depends on the methodology of each report. NAR reports on the median sales price, while some other sources use repeat sales prices. Here’s how those approaches differ.

The Center for Real Estate Studies at Wichita State University explains median prices like this:

The median sale price measures the ‘middle’ price of homes that sold, meaning that half of the homes sold for a higher price and half sold for less . . . For example, if more lower-priced homes have sold recently, the median sale price would decline (because the “middle” home is now a lower-priced home), even if the value of each individual home is rising.”

Investopedia helps define what a repeat sales approach means:

Repeat-sales methods calculate changes in home prices based on sales of the same property, thereby avoiding the problem of trying to account for price differences in homes with varying characteristics.”

The Challenge with the Median Sales Price Today

As the quotes above say, the approaches can tell different stories. That’s why median price data (like EHS) may say prices are down, even though the vast majority of the repeat sales reports show prices are appreciating again.

Bill McBride, Author of the Calculated Risk blog, sums the difference up like this:

“Median prices are distorted by the mix and repeat sales indexes like Case-Shiller and FHFA are probably better for measuring prices.”

To drive this point home, here’s a simple explanation of median value (see visual below). Let’s say you have three coins in your pocket, and you decide to line them up according to their value from low to high. If you have one nickel and two dimes, the median value (the middle one) is 10 cents. If you have two nickels and one dime, the median value is now five cents.


In both cases, a nickel is still worth five cents and a dime is still worth 10 cents. The value of each coin didn’t change.

That’s why using the median home price as a gauge of what’s happening with home values isn’t worthwhile right now. Most buyers look at home prices as a starting point to determine if they match their budgets. But, most people buy homes based on the monthly mortgage payment they can afford, not just the price of the house. When mortgage rates are higher, you may have to buy a less expensive home to keep your monthly housing expense affordable. A greater number of ‘less-expensive’ houses are selling right now for this exact reason, and that’s causing the median price to decline. But that doesn’t mean any single house lost value. 

When you see the stories in the media that prices are falling later this week, remember the coins. Just because the median price changes, it doesn’t mean home prices are falling. What it means is the mix of homes being sold is being impacted by affordability and current mortgage rates.


Monday, May 29, 2023

MEMORIAL DAY 2023

Memorial Day is a day to remember and honor our country's fallen heroes.

All gave some... some gave all.
While Memorial Day weekend marks the unofficial beginning of summer and is typically a time spent celebrating with family and friends, it's important to reflect on the true meaning of the day and take time to remember those who made the ultimate sacrifice to protect the freedoms we cherish.   
 
 
Remember and honor.
Today... and always.


Friday, May 12, 2023

The Worst Home Price Declines Are Behind Us [INFOGRAPHIC]

Infographic Courtesy of Keeping Current Matters/The KCM Blog


Some Highlights

While home prices vary by local area, they’ve already hit their low point nationally, and now they’re starting to rise again.

Last July, prices started to decline, but around February, they began climbing back up.

If you put your plans to move on hold waiting to see what would happen with home prices, reach out to a local real estate expert to discuss if now’s the right time to jump back in.


Thursday, May 4, 2023

How Homeowners Win When They Downsize

Article Courtesy of Keeping Current Matters/The KCM Blog

Downsizing has long been a popular option when homeowners reach retirement age. But there are plenty of other life changes that could make downsizing worthwhile. Homeowners who have experienced a change in their lives or no longer feel like their house fits their needs may benefit from downsizing too. U.S. News explains:

“Downsizing is somewhat common among older people and retirees who no longer have children living at home. But these days, younger people are also looking to downsize to save money on housing . . .”

And when inflation has made most things significantly more expensive, saving money where you can has a lot of appeal. So, if you’re thinking about ways to budget differently, it could be worthwhile to take your home into consideration.

When you think about cutting down on your spending, odds are you think of frequent purchases, like groceries and other goods. But when you downsize your house, you often end up downsizing the bills that come with it, like your mortgage payment, energy costs, and maintenance requirements. Realtor.com shares:

“A smaller home typically means lower bills and less upkeep. Then there’s the potential windfall that comes from selling your larger home and buying something smaller.”

That windfall is thanks to your home equity. If you’ve been in your house for a while, odds are you’ve developed a considerable amount of equity. Your home equity is an asset you can use to help you buy a home that better suits your needs today.

And when you’re ready to make a move, your team of real estate experts will be your guides through every step of the process. That includes setting the right price for your house when you sell, finding the best location and size for your next home, and understanding what you can afford at today’s mortgage rate.

What This Means for You

If you’re thinking about downsizing, ask yourself these questions:

  • Do the original reasons I bought my current house still stand, or have my needs changed since then?
  • Do I really need and want the space I have right now, or could somewhere smaller be a better fit?
  • What are my housing expenses right now, and how much do I want to try to save by downsizing?

Once you know the answers to these questions, meet with a real estate advisor to get an answer to this one: What are my options in the market right now? A local housing market professional can walk you through how much equity you have in your house and how it positions you to win when you downsize.

Bottom Line

If you’re looking to save money, downsizing your home could be a great help toward your goal. Talk with a real estate agent about your goals in the housing market this year.


Monday, May 1, 2023

NEW FANNIE MAE & FREDDIE MAC MORTGAGE RULES

According to the Wall Street Journal and numerous other outlets, if you’re a new homebuyer with good credit (above 680), and you apply for a mortgage backed by Fannie Mae or Freddie Mac – which guarantee the vast majority of all mortgages – then you’re likely to pay hundreds of dollars more in fees known as “loan-level price adjustments.” These fees will be even higher for those who put at least 20% down on their homes!


There are four things I believe this new policy does:

  • It penalizes those who have made the choices necessary to achieve good credit, while rewarding those who have not.
  • It’ll make home ownership even less affordable for those who have demonstrated their ability to live within their means and pay their debts on time.
  • Using other people's money to subsidize loans for lower creditworthy borrowers adds tremendous risk and dysfunction to the housing market.
  • And on top of everything else, it disincentivizes people to save for a larger down payment.
 

Sunday, April 30, 2023

END OF APRIL UPDATE

End of April Stats

SCCL Single Family Residences (SFRs)

  •   6 CURRENTLY ACTIVE
  • 12 WENT UNDER CONTRACT IN APRIL
  •  4 CLOSED IN APRIL
SCCL Carriage Homes and Villas
  •   2  CURRENTLY ACTIVE
  •   1  WENT UNDER CONTRACT IN APRIL
  •   0  CLOSED IN APRIL
TreeTops
  •   4  CURRENTLY ACTIVE (INCLUDES ONE THAT'S "COMING SOON")
  •   2  WENT UNDER CONTRACT IN APRIL
  •   3  CLOSED IN APRIL
There has been quite a range in the number of Days on Market (DOM) for properties that  have closed since the first of the year.  Some homes sold in just a few days, while others lingered for months.  Typically, homes that show really well (uncluttered, fresh paint, great curb appeal) and are priced appropriately for the current market sell faster and at prices closer to asking price - some, at or above list price.  If you look closely at the charts below, you'll notice two columns showing the ratio of Close Price to List Price.  The first CP/LP is based on the most current list price for the property when it sold.  The second, CP/OLP, shows the ratio for the "Original" List Price on the property (when it was first listed) and would indicate that, at some point, there had a price change on the property.

PROPERTIES that have CLOSED since January 1, 2023
Click to enlarge.

SCCL SINGLE FAMILY RESIDENCES


SCCL CARRIAGE HOMES AND VILLAS


TREETOPS


DDP = Due Diligence Period
UCS = Under Contract Show / UCNS = Under Contract No Show
DOM = Days on Market
BR = Bedrooms
BA = Bathrooms
HLA = Heated Living Area (Square Footage)
Price/SF = Price Per Square Foot
UC Date = Under Contract Date


Thursday, April 27, 2023

Why Today's Foreclosure Numbers Are Nothing Like 2008

Article Courtesy of Keeping Current Matters/The KCM Blog

You’ve likely seen headlines about the number of foreclosures climbing in today’s housing market. That may leave you with a few questions, especially if you’re thinking about buying a house. Understanding what they really mean is mission-critical if you want to know the truth about what’s happening today.

According to a recent report from ATTOM, a property data provider, foreclosure filings are up 6% compared to the previous quarter and 22% since one year ago. As media headlines call attention to this increase, reporting on just the number could actually generate worry and may even make you think twice about buying a home for fear that prices could crash. The reality is, while increasing, the data shows a foreclosure crisis is not where the market is headed. 

Let’s look at the latest information with context so we can see how this compares to previous years.

It Isn’t the Dramatic Increase Headlines Would Have You Believe

In recent years, the number of foreclosures has been down to record lows. That’s because, in 2020 and 2021, the forbearance program and other relief options for homeowners helped millions of homeowners stay in their homes, allowing them to get back on their feet during a very challenging period. And with home values rising at the same time, many homeowners who may have found themselves facing foreclosure under other circumstances were able to leverage their equity and sell their houses rather than face foreclosure. Moving forward, equity will continue to be a factor that can help keep people from going into foreclosure.

As the government’s moratorium came to an end, there was an expected rise in foreclosures. But just because foreclosures are up doesn’t mean the housing market is in trouble. As Clare Trapasso, Executive News Editor at Realtor.com, says:

There’s no reason to panic, at least not yet. Foreclosure filings began ticking up . . . after the federal foreclosure moratorium ended. The moratorium was enacted in the early days of COVID-19, when millions of Americans lost their jobs, to prevent a tsunami of homeowners losing their properties. So some of these proceedings would have taken place during the pandemic but got delayed due to the moratorium. This is a bit of a catch-up.”

Basically, there’s not a sudden flood of foreclosures coming. Instead, some of the increase is due to the delayed activity explained above while more is from economic conditions. As Rob Barber, CEO of ATTOM,explains:                                       

This unfortunate trend can be attributed to a variety of factors, such as rising unemployment rates, foreclosure filings making their way through the pipeline after two years of government intervention, and other ongoing economic challenges. However, with many homeowners still having significant home equity, that may help in keeping increased levels of foreclosure activity at bay.”

To further paint the picture of just how different the situation is now compared to the housing crash, take a look at the graph below. It shows foreclosure activity has been lower since the crash by looking at properties with a foreclosure filing going all the way back to 2005.


 While foreclosures are climbing, it’s clear foreclosure activity now is nothing like it was during the housing crisis. In addition to all of the factors mentioned above, that’s also largely because buyers today are more qualified and less likely to default on their loans. 

Today, foreclosures are far below the record-high number that was reported when the housing market crashed.

Bottom Line

Right now, putting the data into context is more important than ever. While the housing market is experiencing an expected rise in foreclosures, it’s nowhere near the crisis levels seen when the housing bubble burst, and that won’t lead to a crash in home prices.
Wednesday, April 26, 2023

The Three Factors Affecting Home Affordability Today

 Article Courtesy of Keeping Current Matters/The KCM Blog

There’s been a lot of focus on higher mortgage rates and how they’re creating affordability challenges for today’s homebuyers. It’s true that rates climbed dramatically since the record-low we saw during the pandemic. But home affordability is based on more than just mortgage rates – it’s determined by a combination of mortgage rates, home prices, and wages.

Considering how each one of these factors is changing gives you the full picture of home affordability today. Here’s the latest.

1. Mortgage Rates

While mortgage rates are higher than they were a year ago, they’ve hovered primarily between 6% and 7% for nearly eight months now (see graph below):


As the graph shows, mortgage rates have experienced some volatility during that time. And even a small change in mortgage rates impacts your purchasing power. That’s why it’s so important to lean on your team of real estate professionals for expert advice to stay up to date on what’s happening in the market. While it’s hard to project where mortgage rates will go from here, many experts agree they’ll likely continue to remain around 6%-7% in the immediate future. 

2. Home Prices

Over the past few years, home prices appreciated rapidly as the record-low mortgage rates we saw during the pandemic led to a surge in buyer demand. The heightened buyer demand happened while the supply of homes for sale was at record lows, and that imbalance put upward pressure on home prices. However, today’s higher mortgage rates have slowed down price appreciation.

And, the truth is, home price appreciation varies by market. Some areas are seeing slight declines while others have prices that are climbing. As Selma Hepp, Chief Economist at CoreLogic, explains:

“The divergence in home price changes across the U.S. reflects a tale of two housing markets. Declines in the West are due to the tech industry slowdown and a severe lack of affordability after decades of undersupply. The consistent gains in the Southeast and South reflect strong job markets, in-migration patterns and relative affordability due to new home construction.”

To find out what’s happening with prices in your local market, reach out to a trusted real estate agent.

3. Wages

The most positive factor in affordability right now is rising income. The graph below uses data from the Bureau of Labor Statistics (BLS) to show how wages have grown over time: 


Higher wages improve affordability because they reduce the percentage of your income it takes to pay your mortgage since you don’t have to put as much of your paycheck toward your monthly housing cost.

Home affordability comes down to a combination of rates, prices, and wages. If you have questions or want to learn more, reach out to a real estate professional who can explain what’s happening locally and how these factors work together.

Bottom Line

If you’re planning to buy a home, knowing the key factors that impact affordability is important so you can make an informed decision. To stay up to date on the latest on each, connect with a trusted real estate professional today.


HOME SELLING MISTAKES THAT CAN COST YOU THOUSANDS OF DOLLARS

 Check out this informative article from SCRIPPS NEWS:  

Home selling mistakes that can cost you thousands of dollars


"The home buying market remains hot due to low inventory. But rookie mistakes can cost homeowners thousands of dollars at sale time."